You could probably name the television, sofa, and laptop in your living room without looking. What about the headphones in the drawer, the small appliances in the kitchen, or everything tucked into the hall closet? A home inventory can help you keep track.
Now imagine trying to reconstruct that list after a fire or theft, while also figuring out where to stay and whom to call.
A home inventory gives you a record you can build while your belongings are still safely in front of you. With holiday purchases approaching, this is a useful time to establish that record and get into the habit of adding new items.
You don’t need to finish the whole house this weekend. One room, a phone or notebook, and a place to save the information can get you started.
What a Home Inventory Does for You
A home inventory documents your belongings and useful details about them. It can include a written list, photographs, video, receipts, and appraisals. The purpose is to make it easier to identify what you own and support the information you provide after a loss.
The National Association of Insurance Commissioners explains that an accurate inventory gives your insurer information to help settle a claim. It also offers an inventory app that groups belongings by room or category and allows you to export your records.
That record doesn’t establish whether a particular loss is covered or guarantee a payment. Coverage still depends on the policy and the circumstances. Instead, the inventory helps answer “What did I have?” so you aren’t relying entirely on memory.
This is useful whether you own or rent your home. If you rent, our guide to what your landlord’s insurance does and doesn’t cover explains why protection for the building and protection for your belongings are separate questions.
Start Your Home Inventory Somewhere You Can Finish
Choose one manageable space, such as a bedroom or a kitchen cabinet. AAA’s inventory guide suggests starting with a small, contained area when the task feels overwhelming.
Pick a format you will actually maintain. A spreadsheet with a folder of photos may suit you. So might an inventory app or a written list backed up with photographs. You can add detail as you go.
For a first session, record what is in one room and save the information somewhere you can find it. Give the folder an obvious name, such as “Home inventory November 2026,” with a subfolder for each room.
Finishing one space gives you a process you can repeat instead of another reason to search for the perfect app.
Capture Details That Will Mean Something Later
A photo of a crowded shelf can show that you had belongings there. A clear record of an individual item gives you more information to work with.
Allstate’s home inventory guidance recommends recording the item type, original price, purchase year, and serial number where applicable. It also recommends photographing rooms and individual belongings, including closets and drawers.
Useful details for an entry include:
- What the item is and where you keep it.
- Brand, model, and serial number, when available.
- Purchase date or approximate year, clearly marked if estimated.
- What you paid, with a receipt or other supporting record if available.
- Photographs showing the item and identifying details.
For example, “television” is less useful than an entry that identifies the brand, model, screen size, purchase year, and location of the receipt. A photograph of the model label can capture details without requiring you to type them immediately.
Ordinary belongings count too. Allstate suggests grouping clothing by type. Give especially valuable items their own entries so they don’t disappear into a broad category.
Use Video as a Starting Point
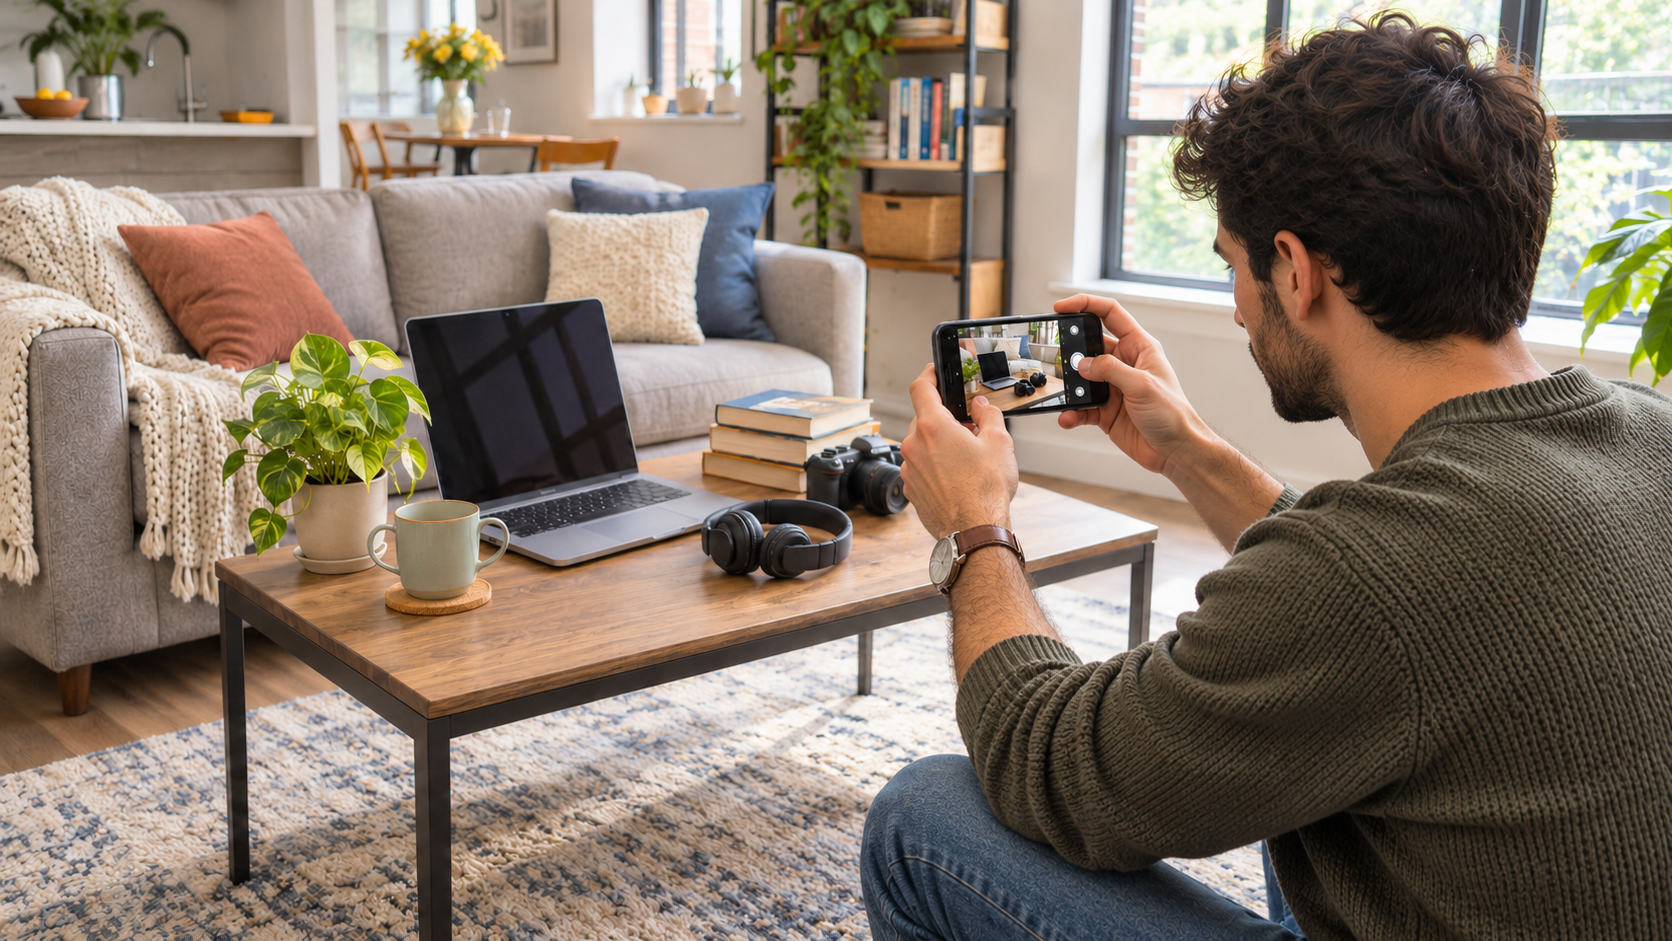
A phone video can capture a room quickly. AAA recommends describing belongings as you record and capturing identifying details. Slow down enough to show what you are discussing, and open accessible cabinets and drawers.
Treat the recording as the beginning of the record. Follow it with closer photographs and notes for items whose details are hard to see. The goal is to leave yourself information you could understand months later.
Think beyond the rooms you use every day as well. Travelers recommends including belongings kept in storage or other locations. Inventorying an item doesn’t establish coverage at that location, but it does give you a record to discuss with your insurer.
Missing Receipts Don’t Have to Stop Your Progress
You may have bought the dining table years ago or received the jewelry as a gift. Record what you can establish now, and identify which details are uncertain.
Allstate lists receipts, bank statements, photographs, and online registrations as examples of ownership documentation. An emailed order confirmation or an account’s purchase history may also help you find information you no longer have on paper.
Keep available records alongside the relevant entry. When a bank statement shows only the retailer and total, add other information that connects the purchase to the item. Ask your insurer what documentation it would need if you made a claim.
Don’t invent a purchase price or date to fill a blank. A clearly labeled estimate is more useful than a precise number you cannot support. You can always improve an incomplete record over time.
Let Your Home Inventory Lead to Coverage Questions
Once you start listing belongings, you may discover that replacing them would cost more than you expected. That makes the inventory useful for a conversation about your personal property coverage.
Travelers explains that some categories have limits below the overall personal property limit. Jewelry, for example, may need separate attention. Ask whether appraisals, scheduled coverage for individual items, or another coverage option would be appropriate for belongings you identify.
Also ask how your policy values a covered item. The NAIC explains that actual cash value considers age and wear, while replacement cost coverage uses the cost of comparable property. Your original purchase price and the cost to replace an item today can differ. Neither figure in your inventory promises what a claim will pay.
Our homeowners coverage guide explains these distinctions in more detail. To locate your coverage amounts and deductible, start with our declarations-page guide, then review the full terms with your insurer or a licensed insurance professional.
Does Your Coverage Fit What You Own?
Have questions about what your policy covers? A licensed insurance agent can help you review your personal property limits, deductible, and coverage options.
Save a Copy You Could Reach After a Loss
An inventory stored only on a damaged or stolen device may be unavailable when you need it. Travelers recommends digital storage you can access from more than one device.
Choose secure storage and check that the files actually uploaded. Try opening the inventory from another device so you know how to retrieve it. If you use an app, confirm how to export the records and keep a backup you can access independently.
The Insurance Information Institute also recommends keeping a backup separately from the original, including an off-site copy of a paper inventory. Your record contains information about your belongings, so keep it private and limit sharing to only the people who need access.
Make New Purchases the Easy Part
Once you have a starting inventory, add significant purchases while the details are fresh. Save the receipt, photograph the item, and update its entry. Remove items you sell or give away so the list continues to reflect what you own.
Holiday shopping gives you a natural opportunity to build that habit. You can also set a reminder to revisit unfinished rooms and review the inventory after a move or other household change.
Start with one room today. You’ll have a record you didn’t have yesterday, plus a process you can repeat. If you ever need to explain what was lost, those details can give you a much better starting point than memory alone.